How Does Cargo Insurance Work, and What Happens When Your Freight Is Damaged?
Cargo insurance covers the value of your freight while a carrier hauls it. When freight arrives damaged, you file a freight claim against the carrier with the bill of lading, delivery receipt, photos, and invoice, and the carrier’s policy pays.
The Moment Every Shipper Dreads
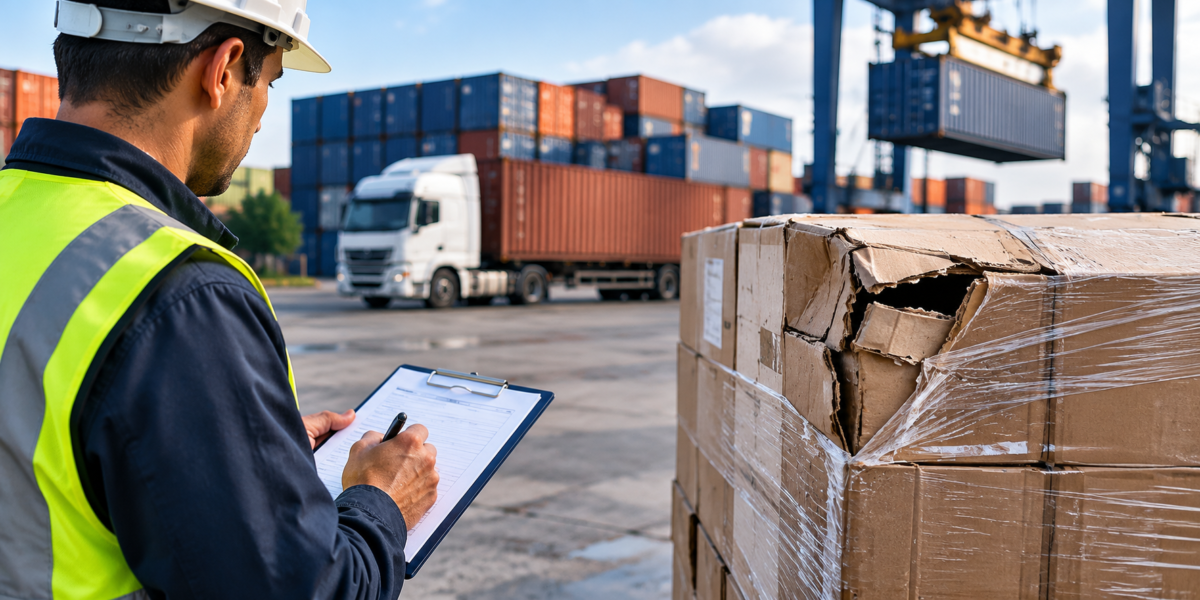
The trailer doors open and something is wrong. Crushed corners, a punctured crate, water stains that weren’t there at pickup. What happens in the next few hours decides whether you recover the full value of that freight or eat the loss, and most shippers don’t learn the rules until they’re already standing on the dock with a camera phone in hand.
Here’s the uncomfortable truth up front: the coverage you think you have is often not the coverage you actually have. At First Class Trucking, we walk shippers through cargo coverage before the first load moves, because the middle of a damage claim is the worst possible time to learn how it works. This guide explains what cargo insurance really covers, how the claim process runs, and the mistakes that get valid claims denied.
What Cargo Insurance in Trucking Actually Covers
Cargo insurance in trucking comes in two forms: the carrier’s legal liability coverage, which pays when the carrier is at fault, and optional all-risk shipper’s insurance, which pays for almost any physical loss regardless of fault.
Every motor carrier hauling interstate freight operates under the Carmack Amendment, which makes them liable for damage to your goods while in their care, with a short list of exceptions like acts of God, public authority, and defects in your own packaging. Carrier liability insurance exists to back that obligation. Federal minimums for that coverage are surprisingly low, which is why reputable carriers carry far more, commonly $100,000 to $1 million per occurrence. Always ask for the certificate and read the number before you book.
The catch is that carrier liability pays up to the carrier’s stated limit and applies only when the carrier is legally liable. All-risk cargo insurance, the kind you buy as a shipper or add per shipment, covers the gaps: weather events, theft under circumstances liability disputes, and losses where fault gets murky. If your freight’s value would hurt to lose, the few dollars per hundred dollars of value that all-risk coverage costs is the easiest insurance decision in logistics.
| Coverage Type | What It Is | What It Pays |
|---|---|---|
| Carrier legal liability | Required coverage backing the carrier’s fault-based obligation under the Carmack Amendment | Up to the carrier’s per-occurrence limit, only when the carrier is at fault |
| Released value rate | Reduced freight rate in exchange for capped carrier liability (often cents per pound) | The released rate, not your invoice value |
| All-risk shipper’s insurance | Optional policy you purchase per shipment or annually | Full declared value for almost any physical loss or damage |
The Released-Value Trap That Costs Shippers Real Money
If your rate is based on released value, the carrier’s payout is capped at a per-pound figure that can be a fraction of your freight’s actual worth. Always check whether your quote is released value or full liability before you sign.
Here’s the math that stings. Say a 2,000-pound pallet of electronics worth $40,000 ships under a released value of $0.50 per pound, a figure you accepted because the rate looked great. The pallet is destroyed in transit. The carrier’s legal obligation: $1,000. That’s the whole claim. Released value agreements are legal, common in LTL tariffs, and buried in paperwork most shippers never read. The fix costs one sentence at booking: ask whether the rate is released or full liability, and declare the actual value.
Declared value is the middle path: you tell the carrier what the freight is worth, pay a small surcharge, and their liability rises to match. For anything dense and valuable, electronics, machinery, pharmaceuticals, declared value or a separate all-risk policy isn’t optional. It’s the difference between a bad day and a bad quarter.
The Cargo Claim Process, Step by Step
The cargo claim process runs in five steps: inspect at delivery, note damage on the proof of delivery, document everything, file a written claim with the carrier, and track it through acknowledgment to resolution.
- 1. Inspect at delivery. Open and check before the driver leaves when you can. Damage noted at delivery is nearly impossible to dispute later.
- 2. Write exceptions on the delivery receipt. “Two cartons crushed, right rear pallet shifted.” A clean signature is treated as proof the freight arrived perfect. Never sign clean on damaged freight.
- 3. Photograph everything. The freight, the packaging, the trailer interior if you can, and the paperwork. Photos taken at the dock beat arguments made weeks later.
- 4. File the written claim. Send the carrier the claim amount with the bill of lading, the annotated delivery receipt, the commercial invoice, photos, and repair or replacement estimates. Federal rules give you at least nine months from delivery, but file within days while evidence is fresh.
- 5. Track the timeline. The carrier must acknowledge your claim within 30 days and pay, offer a settlement, or deny it within 120 days. Diary those dates and follow up in writing.
Everything in a freight claim leans on two documents: the bill of lading that started the move and the proof of delivery that ended it. We published a full walkthrough of how the bill of lading and proof of delivery work together, and if you ship with any regularity, it’s worth five minutes of your time before you ever need it.
Who Answers the Claim on Brokered Freight?
On brokered freight, the claim is filed against the carrier that physically hauled the load, not the broker who arranged it, which is why the carrier’s identity and insurance certificate matter from day one.
This is where brokered shipments get painful. The broker’s usual role in a claim is messenger: they pass your paperwork to whichever carrier took the load, and you’re now chasing a company you never chose, whose insurance you’ve never seen. Sometimes that carrier is excellent. Sometimes it’s a one-truck operation with lapsed coverage, and the broker’s bond was never designed to cover your cargo.
With an asset-based carrier, the company you hired is the company that hauled the freight, and its own cargo policy answers the claim. One throat to choke, as the old industry saying goes. We compared the accountability chain in detail in our guide to choosing an asset-based carrier vs broker, and claims are where the difference stops being theoretical.
Five Mistakes That Get Freight Claims Denied
Most freight claims die from five errors: a clean-signed delivery receipt, late filing, no photos, poor original packaging, and claiming costs the carrier never owed.
- 1. The clean signature. Sign “received in good condition” on damaged freight and the claim is nearly dead on arrival. Note exceptions every single time.
- 2. Waiting to file. Memories fade, evidence disappears, and carriers notice. File within days, not months.
- 3. No photographs. Your word against a denial letter loses. Timestamped dock photos win.
- 4. Bad packaging. If the box failed because it was under-built for LTL handling, that’s the shipper’s defect exclusion, and carriers will prove it with photos of their own.
- 5. Claiming consequential damages. Carrier liability covers the freight’s value, not your lost sale, your customer’s penalty, or your production downtime. Only the freight itself, unless you negotiated more in writing.
None of these require a lawyer to avoid. They require a dock routine: inspect, annotate, photograph, file fast. Build the habit before you need it.
How We Handle Cargo Coverage at First Class Trucking
First Class Trucking hauls every load under our own cargo liability policy, hands over insurance certificates on request, and gives you one accountable point of contact if anything ever goes wrong.
Because we’re an asset-based carrier, the claim scenario this article warns about doesn’t apply to our loads: no mystery carrier, no relayed paperwork, no broker bond runaround. Our dispatch team is live 24/7 if you need to report damage, our tracking gives you the delivery record, and the same accountability runs across all our trucking services, from LTL to oversized. With a 95%+ on-time delivery rate and airlines like Emirates SkyCargo, DHL, and Delta trusting us with their ground freight, our standard is simple: freight arrives intact, or we own the fix.
Ask about our cargo coverage before you book and we’ll send the certificate with your quote, along with zero down payment booking and our price beat guarantee.
Frequently Asked Questions
Q: Is cargo insurance required by law for trucking companies?
A: Yes and no. Interstate motor carriers must carry minimum cargo liability coverage under FMCSA rules, but the federal minimums are low, and the real question is how much coverage the carrier carries beyond them. Always ask for the certificate of insurance and check the per-occurrence limit against your freight’s value.
Q: How much cargo coverage do I actually need?
A: Match coverage to your single most expensive shipment, not your average one. If one trailer of your product is worth $80,000, a carrier with $100,000 per-occurrence coverage is fine. If it’s worth $400,000, you need declared value, a high-limit carrier, or your own all-risk policy.
Q: How long does a freight claim take?
A: Federal rules require the carrier to acknowledge your claim within 30 days and to pay, settle, or deny within 120 days. Well-documented claims against responsive carriers often settle faster. Poorly documented ones stall, which is why the dock photos and annotated delivery receipt matter so much.
Q: What is the deadline to file a freight claim?
A: Under the Carmack Amendment framework, you have a minimum of nine months from the delivery date to file a written claim. Some contracts shorten or extend this. Treat nine months as the outer limit, not the plan: file within days while the evidence is fresh.
Q: Does carrier liability cover the full value of my freight?
A: Not automatically. Coverage pays up to the carrier’s limit, and released-value rates cap payouts at a per-pound figure far below invoice value. For full protection, declare the value with the carrier or buy all-risk shipper’s insurance.
Q: Can I buy extra cargo coverage for just one shipment?
A: Yes. Single-shipment all-risk policies are widely available and inexpensive relative to cargo value, typically priced per hundred dollars of declared value. For one-off high-value loads, it’s the simplest way to remove the liability question entirely.
Q: What if the broker’s carrier damaged my freight?
A: File the claim against the carrier that hauled the load; their name is on the bill of lading and their policy is the one that responds. A good broker will help you pursue it, but they aren’t legally on the hook for the cargo. This is why knowing the actual carrier’s identity and insurance before pickup matters.
Book Freight That Comes With Real Coverage
Cargo insurance questions are cheapest before the load moves. Tell us what you’re shipping and what it’s worth, and First Class Trucking will quote it with the coverage documented, the certificate available, and one accountable team behind the freight. Zero down payment to book, and our price beat guarantee applies to any comparable written quote.
| COVERAGE CERTIFICATES ON REQUEST Call (954) 228-2441 or email sales@truckfirstclass.com. Live dispatch answers 24/7, 365 days a year. |